
SIP for ₹50 Lakh Goal: A Practical Roadmap to a Mid-Term Wealth Milestone

8 Views
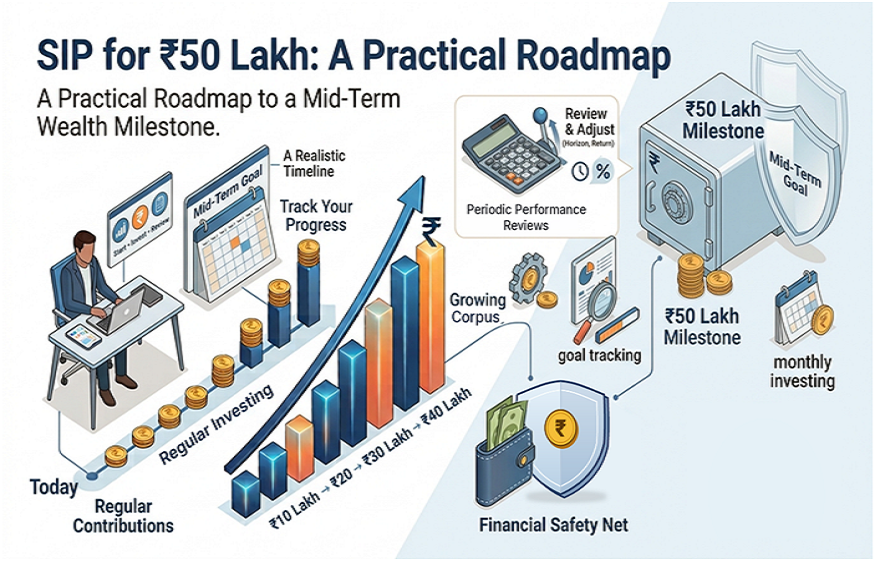
A ₹50 lakh corpus can be an important wealth milestone for an investor. It may represent the foundation for a home purchase, children’s education, retirement planning, financial independence or simply a larger investment portfolio. Unlike very short-term financial goals, building ₹50 lakh typically requires patience, disciplined investing and a clearly defined time horizon.
A systematic investment plan (SIP) can help convert this large target into manageable monthly contributions. However, the right SIP for 50 lakh depends on how soon you want to reach the goal, your existing investments and the return assumption used for planning.
Begin With Your Timeline
The first question is not how much you should invest every month, but when you need the ₹50 lakh corpus. A sip calculator can help estimate the monthly investment required based on your target amount, investment horizon and assumed rate of return.
Read More : Why Global Exposure Matters More as Gulf Economies Continue to Diversify
For illustration, assuming an annualised return of 10%:
- 10 years: approximately ₹24,400 per month
- 12 years: approximately ₹18,000 per month
- 15 years: approximately ₹12,100 per month
- 20 years: approximately ₹6,600 per month
These figures are mathematical illustrations and not guaranteed investment outcomes. Actual mutual fund returns can fluctuate depending on market conditions and the investments selected. The numbers also demonstrate the role of time. Extending the investment horizon can reduce the monthly amount required, although it also means postponing the achievement of the goal.
Why ₹50 Lakh Is a Useful Milestone
₹50 lakh can serve as a practical halfway point between smaller savings targets and larger long-term wealth objectives.For example, someone may initially aim to accumulate ₹10 lakh, then ₹25 lakh and eventually ₹50 lakh. Breaking a large financial objective into milestones can make long-term investing easier to track.Importantly, the ₹50 lakh target should have a purpose. A corpus intended for retirement should be evaluated differently from one intended for a home down payment or a child’s education.
Your goal determines the time horizon, risk capacity and investment approach.
Consider Inflation Before Setting the Target
A ₹50 lakh goal should not automatically be treated as a fixed future requirement.If your objective is to accumulate ₹50 lakh in today’s purchasing power, inflation needs to be considered. At an assumed inflation rate of 6%, ₹50 lakh today would require approximately ₹89.7 lakh after 10 years to maintain equivalent purchasing power.
This is why investors should distinguish between “₹50 lakh as a future corpus” and “₹50 lakh worth of today’s purchasing power.”The distinction can materially change the SIP required.
Increase the SIP as Your Income Grows
A fixed SIP can be a good starting point, but income rarely remains unchanged throughout a career.An annual SIP step-up can help align investments with rising earnings.
For example, an investor starting with a ₹15,000 monthly SIP could increase the contribution periodically as their salary or business income rises.This approach can help accelerate the journey toward the target without requiring an unusually high monthly contribution from the beginning.Bonuses, incentives or other occasional income can also be directed toward the goal, provided other financial priorities are adequately covered.
Match Investment Risk With the Time Horizon
The investment strategy for a 15- or 20-year goal may differ from one for a three- or five-year objective.With a longer horizon, investors may have greater capacity to tolerate short-term market fluctuations, depending on their risk profile. As the ₹50 lakh goal approaches, protecting the accumulated corpus becomes increasingly important.
If the money is required within a short period, taking excessive market risk to compensate for a shortfall can create additional uncertainty. Periodic portfolio reviews can help ensure that the investment approach remains aligned with the remaining timeline.
Track the Corpus, Not Just the SIP
Investors often focus on whether they are investing the required amount every month. But tracking the actual portfolio value is equally important.
Review your progress periodically against:
Target corpus → Current corpus → Time remaining → Monthly SIP → Expected return
If the portfolio is falling behind the target, you can reassess the variables rather than immediately increasing investment risk.You could increase the SIP, introduce an annual step-up, add occasional investments or extend the goal timeline.
Make ₹50 Lakh a Milestone in a Larger Plan
The value of an SIP for 50 lakh lies in turning an intimidating number into a structured financial objective.
consider asking:What is the purpose of the corpus? When will I need it? How much will I need after accounting for inflation? And how much can I invest consistently?
Once these questions are answered, the SIP becomes a tool for executing the plan rather than the plan itself.A ₹50 lakh corpus can be a meaningful mid-term wealth milestone, but its real significance depends on what it enables you to achieve. Start with a realistic target, invest consistently, increase contributions as your financial capacity improves and review the plan as your circumstances change.
Read More : Active Investing: A Hands-On Approach to Building Wealth
Disclaimer: This article is for educational purposes only and should not be considered investment advice. All calculations and inflation assumptions are illustrative; actual investment outcomes may differ.
More Stories
Why Global Exposure Matters More as Gulf Economies Continue to Diversify
The Gulf is entering a new economic era. Oil and gas remain important to the region, but countries across the...
Active Investing: A Hands-On Approach to Building Wealth
Active investing is a strategy that requires attention, timing, and deep market insight. Unlike passive strategies that rely on broad...
Investing Made Easy: How Modern Apps Are Changing the Way Indians Manage Their Portfolios
The Indian investment ecosystem has undergone a rapid change in the last few years. The key drivers were the growing...
What is a Flexi Cap Fund? Benefits and Why You Should Invest
More people now prefer mutual funds as their chosen investment vehicle to build their wealth throughout their financial journey. The...
Understanding index ETFs: Investing in the market’s performance
As the stock market continues to grow and evolve, investors are presented with many options for investing in equities. One...
How To Manage Your ULIP Investment If You Are a New Investor?
Unit linked insurance plan, or ULIP, is investment-cum-insurance plan. In ULIP, a part of the investment is put towards providing...